Owning your business premises is a significant milestone for any UK SME. Beyond saving on rent, a commercial mortgage can provide long-term stability and a valuable asset for your company’s balance sheet. However, the application process can be complex. To help you prepare, we’ve put together this essential checklist for securing your commercial mortgage.
1. Financial Documentation is Key
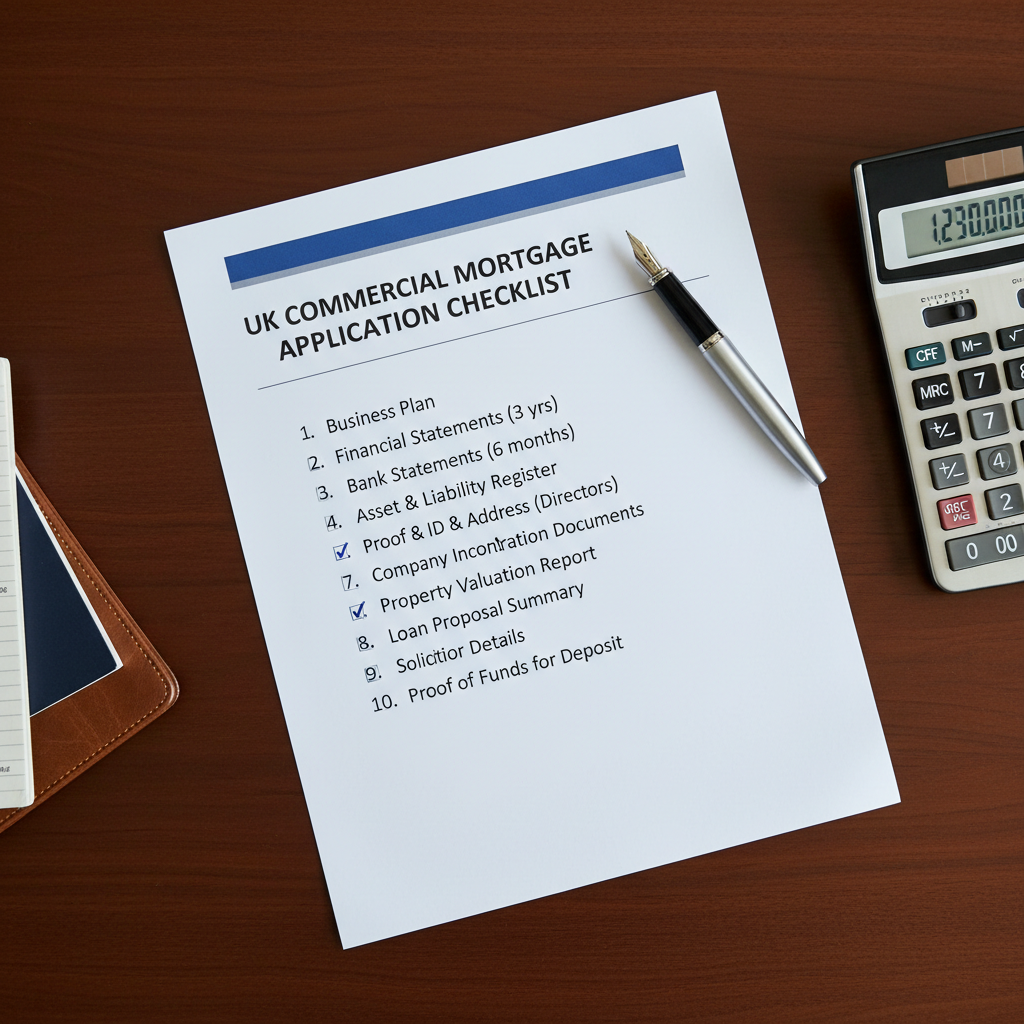
Lenders will want a deep dive into your financial health. Ensure you have the following ready:
- Last 3 years of audited accounts.
- Recent bank statements (usually last 6 months).
- A clear business plan outlining future projections.
- Proof of deposit (typically 20% to 30%).
2. Property Details and Valuation
The lender will perform their own valuation, but you should have all the details regarding the property’s usage, condition, and location. Understanding whether the property is freehold or leasehold is also crucial, as this significantly impacts the mortgage terms. At Neo Business Finance, we work with a wide panel of lenders to find the most competitive commercial mortgage rates for our clients.